What is the Financial Advice Gap?
Rising cost of living and falling adviser numbers are creating a financial advice gap. What exactly is it, what's causing it, and what can be done about it?
Feeling overwhelmed by your finances? You're not alone.
According to AMP’s 2024 Financial Wellness report, 2 in 3 Australians are feeling financially stressed to some degree. That’s the highest that figure has been since 2014.
It’s not hard to see why. With Australia’s cost of living crisis, essential items such as rent, food, and utilities are taking bigger and bigger bites out of each pay cheque.
When money is tight, there’s less room for error. So, making smart money decisions has never been more important. But few Australians feel equipped to make these decisions on their own.
You might think to turn to a financial adviser for guidance. But for millions of Australians, that much needed guidance is far out of reach.
The 2025 Financial Advice Report from Investment Trends found that 15.9 million Australians have advice needs that are not being met.
This disconnect between the number of Australians who need financial advice and those who can access it is known as the financial advice gap.
But how exactly did we get here? And, more importantly, what can be done about it?
Falling Adviser Numbers
The financial advice gap is primarily caused by a fundamental shortage in the number of qualified advisers available.
The number of financial advisers in Australia has plummeted in the last few years, from around 28,000 advisers in 2018 to 15,099 in mid-2026 - a drop of roughly 46%.
The drop in numbers is largely due to the Hayne Royal Commission and the subsequent reforms which reshaped the industry.
Officially the Royal Commission into Misconduct in the Banking, Superannuation and Financial Services Industry, the Commission was initiated in 2017 to investigate and report on misconduct in these industries.
The investigation was concluded in 2019 and found that conflicts of interest, poor ethical standards, and inappropriate or misleading advice were widespread.
In almost every case, the conduct in issue was driven not only by the relevant entity's pursuit of profit but also by individuals' pursuit of gain, whether in the form of remuneration for the individual or profit for the individual's business. Providing a service to customers was relegated to second place. -Commissioner Kenneth Hayne AC, 2019
In other words, clients were being told to purchase financial products that would benefit the adviser in some way, rather than those that were in their best interests.
In response, the Australian government introduced new ethical standards, and greatly increased educational standards and reporting and disclosure requirements for financial advisers.
These reforms were long overdue. But many existing advisers couldn’t, or chose not to, meet the newly increased educational standards and instead simply left the industry.
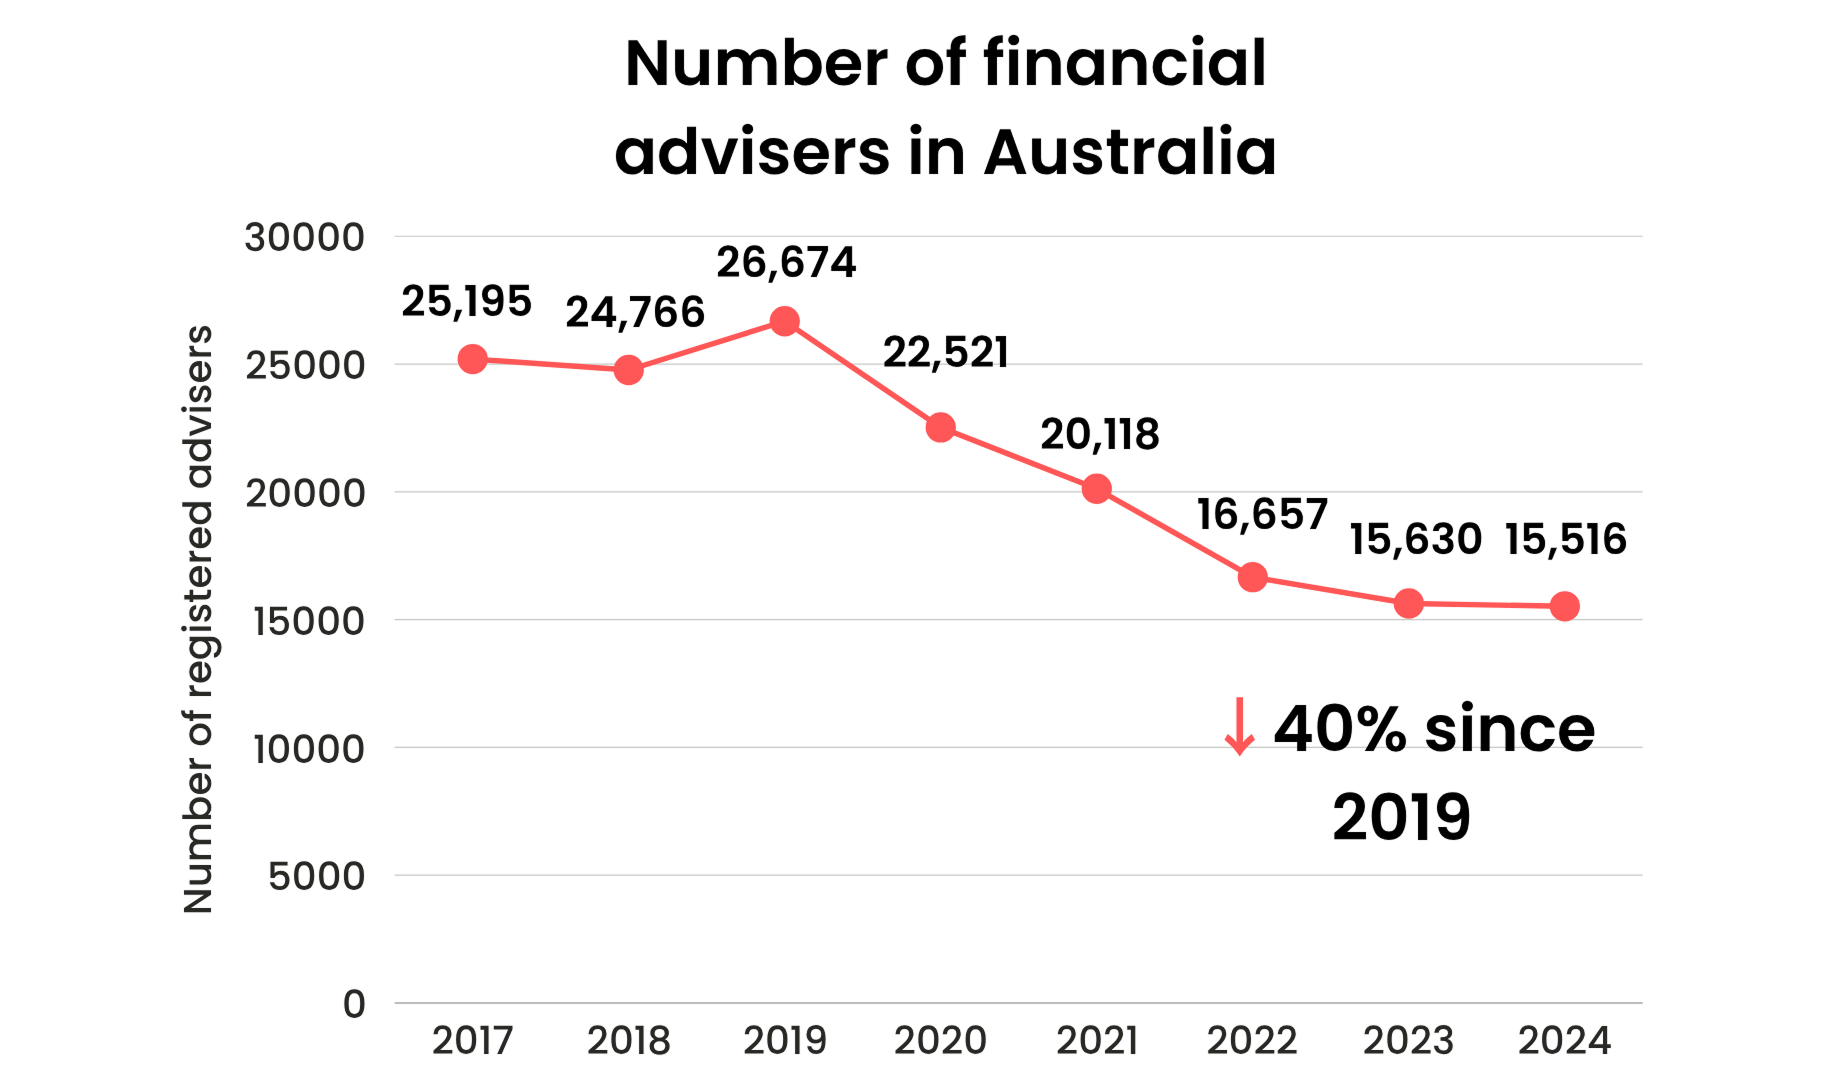
At the same time, rising compliance costs pushed many institutions out of advice altogether. Australia’s big banks, once among the largest employers of advisers, sold off or shut down their advice businesses.
The shortage of qualified advisers and increased compliance costs have caused the cost of financial advice to surge from $2,510 in 2019 to $4,668 in 2025, according to Adviser Ratings.
Cost of Living Crisis
While the supply of financial advice has been shrinking, demand for it has been growing.
Australians are grappling with an ongoing cost of living crisis.
With the cost of everyday expenses continuing to rise, Australians are being forced to make tougher financial decisions about how to spend, save, and plan for the future.
According to Adviser Ratings’ 2025 Australian Financial Advice Landscape Report, consumer demand for financial advice has risen significantly, with leads on the platform up 189% since 2020.
But the same pressure that’s pushing people towards advice is also pricing them out of it. As Adviser Ratings puts it, rising living costs heighten consumer awareness of the need for advice while simultaneously reducing their ability to afford it. Australians without an adviser were found to be willing to pay an average of $553 for financial advice.
Young Australians Hit Hardest
The demand for advice is particularly strong for younger generations.
Research by ASIC's Moneysmart program found that financial stress is particularly high for Gen Z, with 7 in 10 reporting finances are a major source of concern (versus 57% for other generations).
The same research also found that Gen Z is twice as likely as other generations to want to better manage their finances.
But even when they can pay, young people are rarely a priority. Advisers are increasingly focusing only on wealthy clients, which Adviser Ratings describes as “a direct response to rising advice delivery costs and ongoing regulatory requirements that make serving lower-value clients increasingly challenging.”
Since professional financial advice is out of the picture, young Australians are increasingly turning to social media for advice. ASIC found that 63% of Gen Z Australians already rely on social media for financial information.
That’s a problem. Social media is designed to maximise attention, and ASIC warns that content is frequently incomplete, promotional, or misleading.
This coincides with a rise in the popularity of cryptocurrencies and other speculative trading strategies, the sort of content that frequently goes viral on social media.
For a generation that is feeling increasingly pessimistic about their future, it’s easy to see the appeal. Traditional wealth building strategies can hardly keep pace with the cost of living, so speculation starts to feel like the only option to catch up.
How do we fix this?
The need for accessible and affordable financial advice is clear.
More advisers is obvious. But education requirements make It is also clear that the only way to provide financial advice affordably and scalably is through technology.
For the most basic financial needs, digital advice tools can provide quality financial advice at a fraction of the cost of a human adviser.
Technology has its own limitations, but it is the future.
By carefully embracing that future, and keeping in mind the lessons of the past, we can finally bridge the financial advice gap and restore hope to the millions of Australians in need.
That's exactly what we're doing at Pocket Adviser.
This article is intended for educational purposes only. The information provided is general in nature and does not consider your personal financial circumstances. Please consult a licensed financial adviser if you require advice.